Along Florida’s Scenic Highway 30A, luxury real estate operates on its own unique frequency. From the pristine white sands of WaterColor and Seaside to the Mediterranean-inspired architecture of Alys Beach and Rosemary Beach, high-end coastal property remains a prized asset class.
However, the prolonged environment of elevated mortgage interest rates has introduced a new layer of sophistication and intentionality to our market. While high borrowing costs have slowed secondary and tertiary residential housing markets nationwide, 30A’s unique blend of scarcity, high-net-worth buyers, and lifestyle appeal has created a distinctly segmented landscape.
Whether you are looking to acquire a primary beach estate or liquidate a high-performing investment property, understanding how today’s rate climate shapes negotiations is critical.
The Impact of Higher Interest Rates on 30A
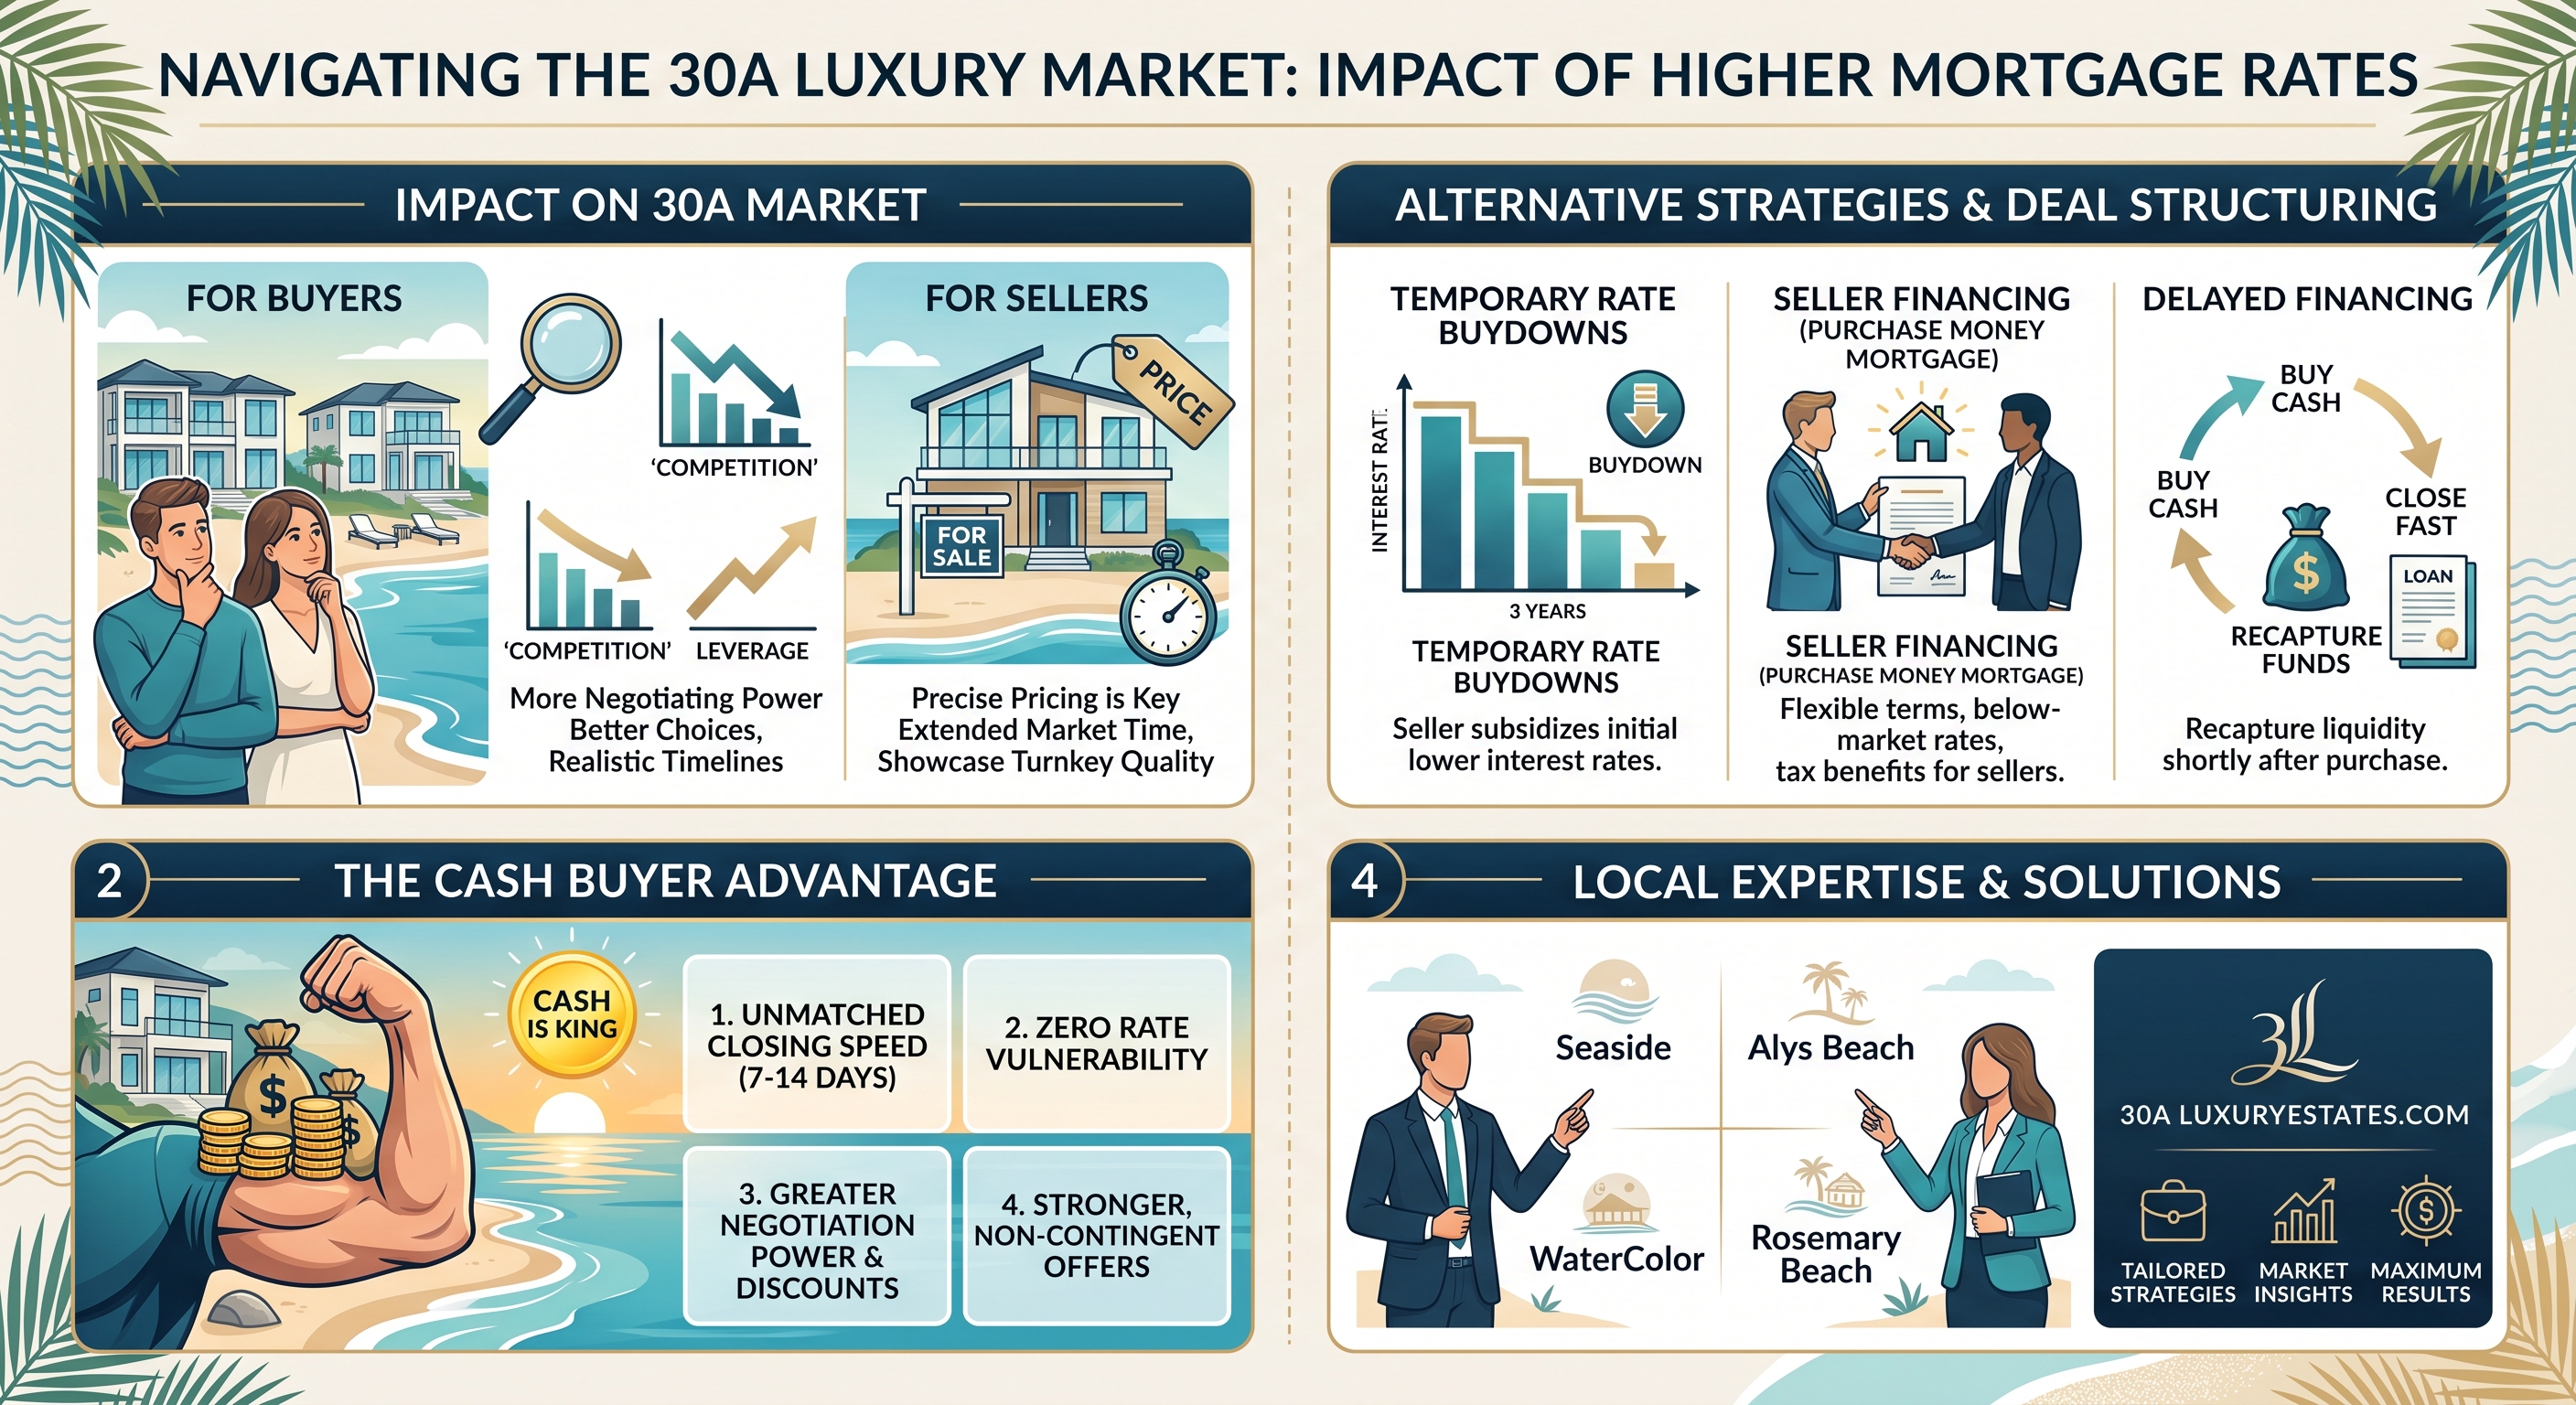
For Buyers: More Leverage, Better Choices, and No Rush
The frantic, emotional bidding wars of previous years have given way to a disciplined market. Higher borrowing costs have removed speculative, highly leveraged buyers from the pool.
Greater Negotiating Power: With properties spending more realistic average timelines on the market, buyers have time to perform thorough due diligence, compare master-planned communities, and negotiate on price, contingencies, or seller concessions.
Selective Inventory Growth: Buyers no longer face the pressure to write a non-contingent offer on day one. They can evaluate layout quality, HOA structures, and projected rental yields with clarity.
For Sellers: Precision Pricing Is Essential
The days of launching an listing with an inflated price tag and watching multiple offers roll in are over.
The Pricing Gap: Exceptional homes—those with prime Gulf proximity, fresh architectural design, or turnkey condition—continue to fetch top dollar. However, secondary properties or homes requiring updates that are priced at the peak of the market risk idling.
Carrying Costs Matter: Higher rates, paired with evolving insurance and maintenance expenses, mean sellers must focus on realistic valuation and crisp presentation from day one.
The Cash Buyer’s Advantage on 30A
Cash has always played a prominent role along 30A, but in a higher-rate market, all-cash buyers wield unprecedented leverage.
Unrivaled Closing Speed & Certainty: In luxury transactions, certainty is often more valuable to a seller than a slightly higher purchase price. Cash buyers can bypass time-consuming underwriting, property appraisals, and lender approvals, offering a clean 7- to 14-day timeline to closing.
Substantial Purchase Discounts: Sellers know that financed deals carry financing and appraisal contingencies that can fall through. Cash buyers routinely leverage this certainty to secure favorable price discounts or seller credits.
Freedom from Yield Compression: While leveraged buyers see their net rental yields compressed by higher debt service payments, cash buyers capture the full cash flow from short-term rental properties from day one.
Alternative Financing & Strategic Deal Structuring
If you want to acquire a 30A property without tying up liquidity or taking on standard 30-year fixed bank debt at current market rates, several alternative strategies allow you to navigate this environment effectively:
1. Temporary & Permanent Interest Rate Buydowns
Sellers eager to attract financed buyers often offer concessions rather than upfront price cuts. Using a 2-1 Buydown (where the interest rate is reduced by 2% in year one and 1% in year two) or a 3-1 Buydown, the seller subsidizes lower monthly payments for the buyer during the initial ownership period.
2. Seller Financing (Purchase Money Mortgages)
Many 30A homeowners hold significant equity in their properties with no outstanding mortgage debt. In these cases, buyers and sellers can negotiate seller financing directly:
Benefits for Buyers: Secure below-market interest rates, flexible loan terms, reduced closing costs, and no rigid institutional loan underwriting.
Benefits for Sellers: Create a steady, income-producing asset backed by real estate equity, defer capital gains taxes through installment sale treatment, and command a strong overall sale price.
3. Delayed Financing
For buyers who want the competitive advantage of a cash offer but ultimately prefer to keep their capital deployed elsewhere:
Purchase the home using 100% liquid cash to win the deal and secure a fast closing.
Immediately post-closing, apply for a Delayed Financing mortgage.
Recapture up to 70–80% of the home's appraised value as cash within 90 days of closing without waiting for standard seasoning periods.
4. Adjustable-Rate Mortgages (ARMs) & Portfolio Lenders
For luxury second homes, short-term hybrid ARMs (e.g., 5/1, 7/1, or 10/1 ARMs) frequently offer lower starting rates than standard 30-year fixed loans. Working with regional portfolio lenders who understand the unique dynamics of Walton County luxury real estate can also open doors to tailored loan structures, asset-based lending, or custom debt schedules.
Navigating the 30A Market with 30A Luxury Estates
In a market defined by selectivity and strategy, having local guidance makes all the difference. Whether you are a cash buyer looking to capitalize on inventory opportunities or a seller aiming to position your property for maximum yield, our team at 30A Luxury Estates provides the insights and deal-structuring expertise you need.
Ready to discuss your 30A real estate goals? Contact Robert Stenhammer today for a private consultation or market evaluation.
Socials