For high-net-worth investors, real estate wealth management is as much about capital preservation and tax efficiency as it is about appreciation. When divesting from high-tax states or rebalancing multi-million-dollar property portfolios, federal capital gains taxes and state income taxes can erode up to 30% to 40% of realized equity.
Section 1031 of the Internal Revenue Code remains one of the most powerful wealth-preservation vehicles available to real estate investors. By deferring federal capital gains taxes, depreciation recapture, and the 3.8% Net Investment Income Tax (NIIT), investors can reallocate 100% of their equity into prime, yield-generating luxury real estate along Florida's Scenic Highway 30A.
Why 30A is a Premier 1031 Exchange Destination
Florida’s Scenic Highway 30A—home to master-planned coastal enclaves like Rosemary Beach, Alys Beach, WaterColor, and Watersound—offers a distinct economic environment for exchange capital:
Zero Florida Income Tax: Deferring federal liabilities while acquiring assets in a tax-friendly jurisdiction keeps ongoing income shielded at the state level.
Scarcity & Long-Term Appreciation: Geographic constraints between the Gulf of Mexico and coastal dune lakes limit future supply, insulating long-term asset valuations.
High-Performing Rental Yields: Multi-bedroom luxury beachfront estates routinely generate significant short-term rental revenue, helping offset debt service or fund reinvestments.
The Core Timelines You Cannot Afford to Miss
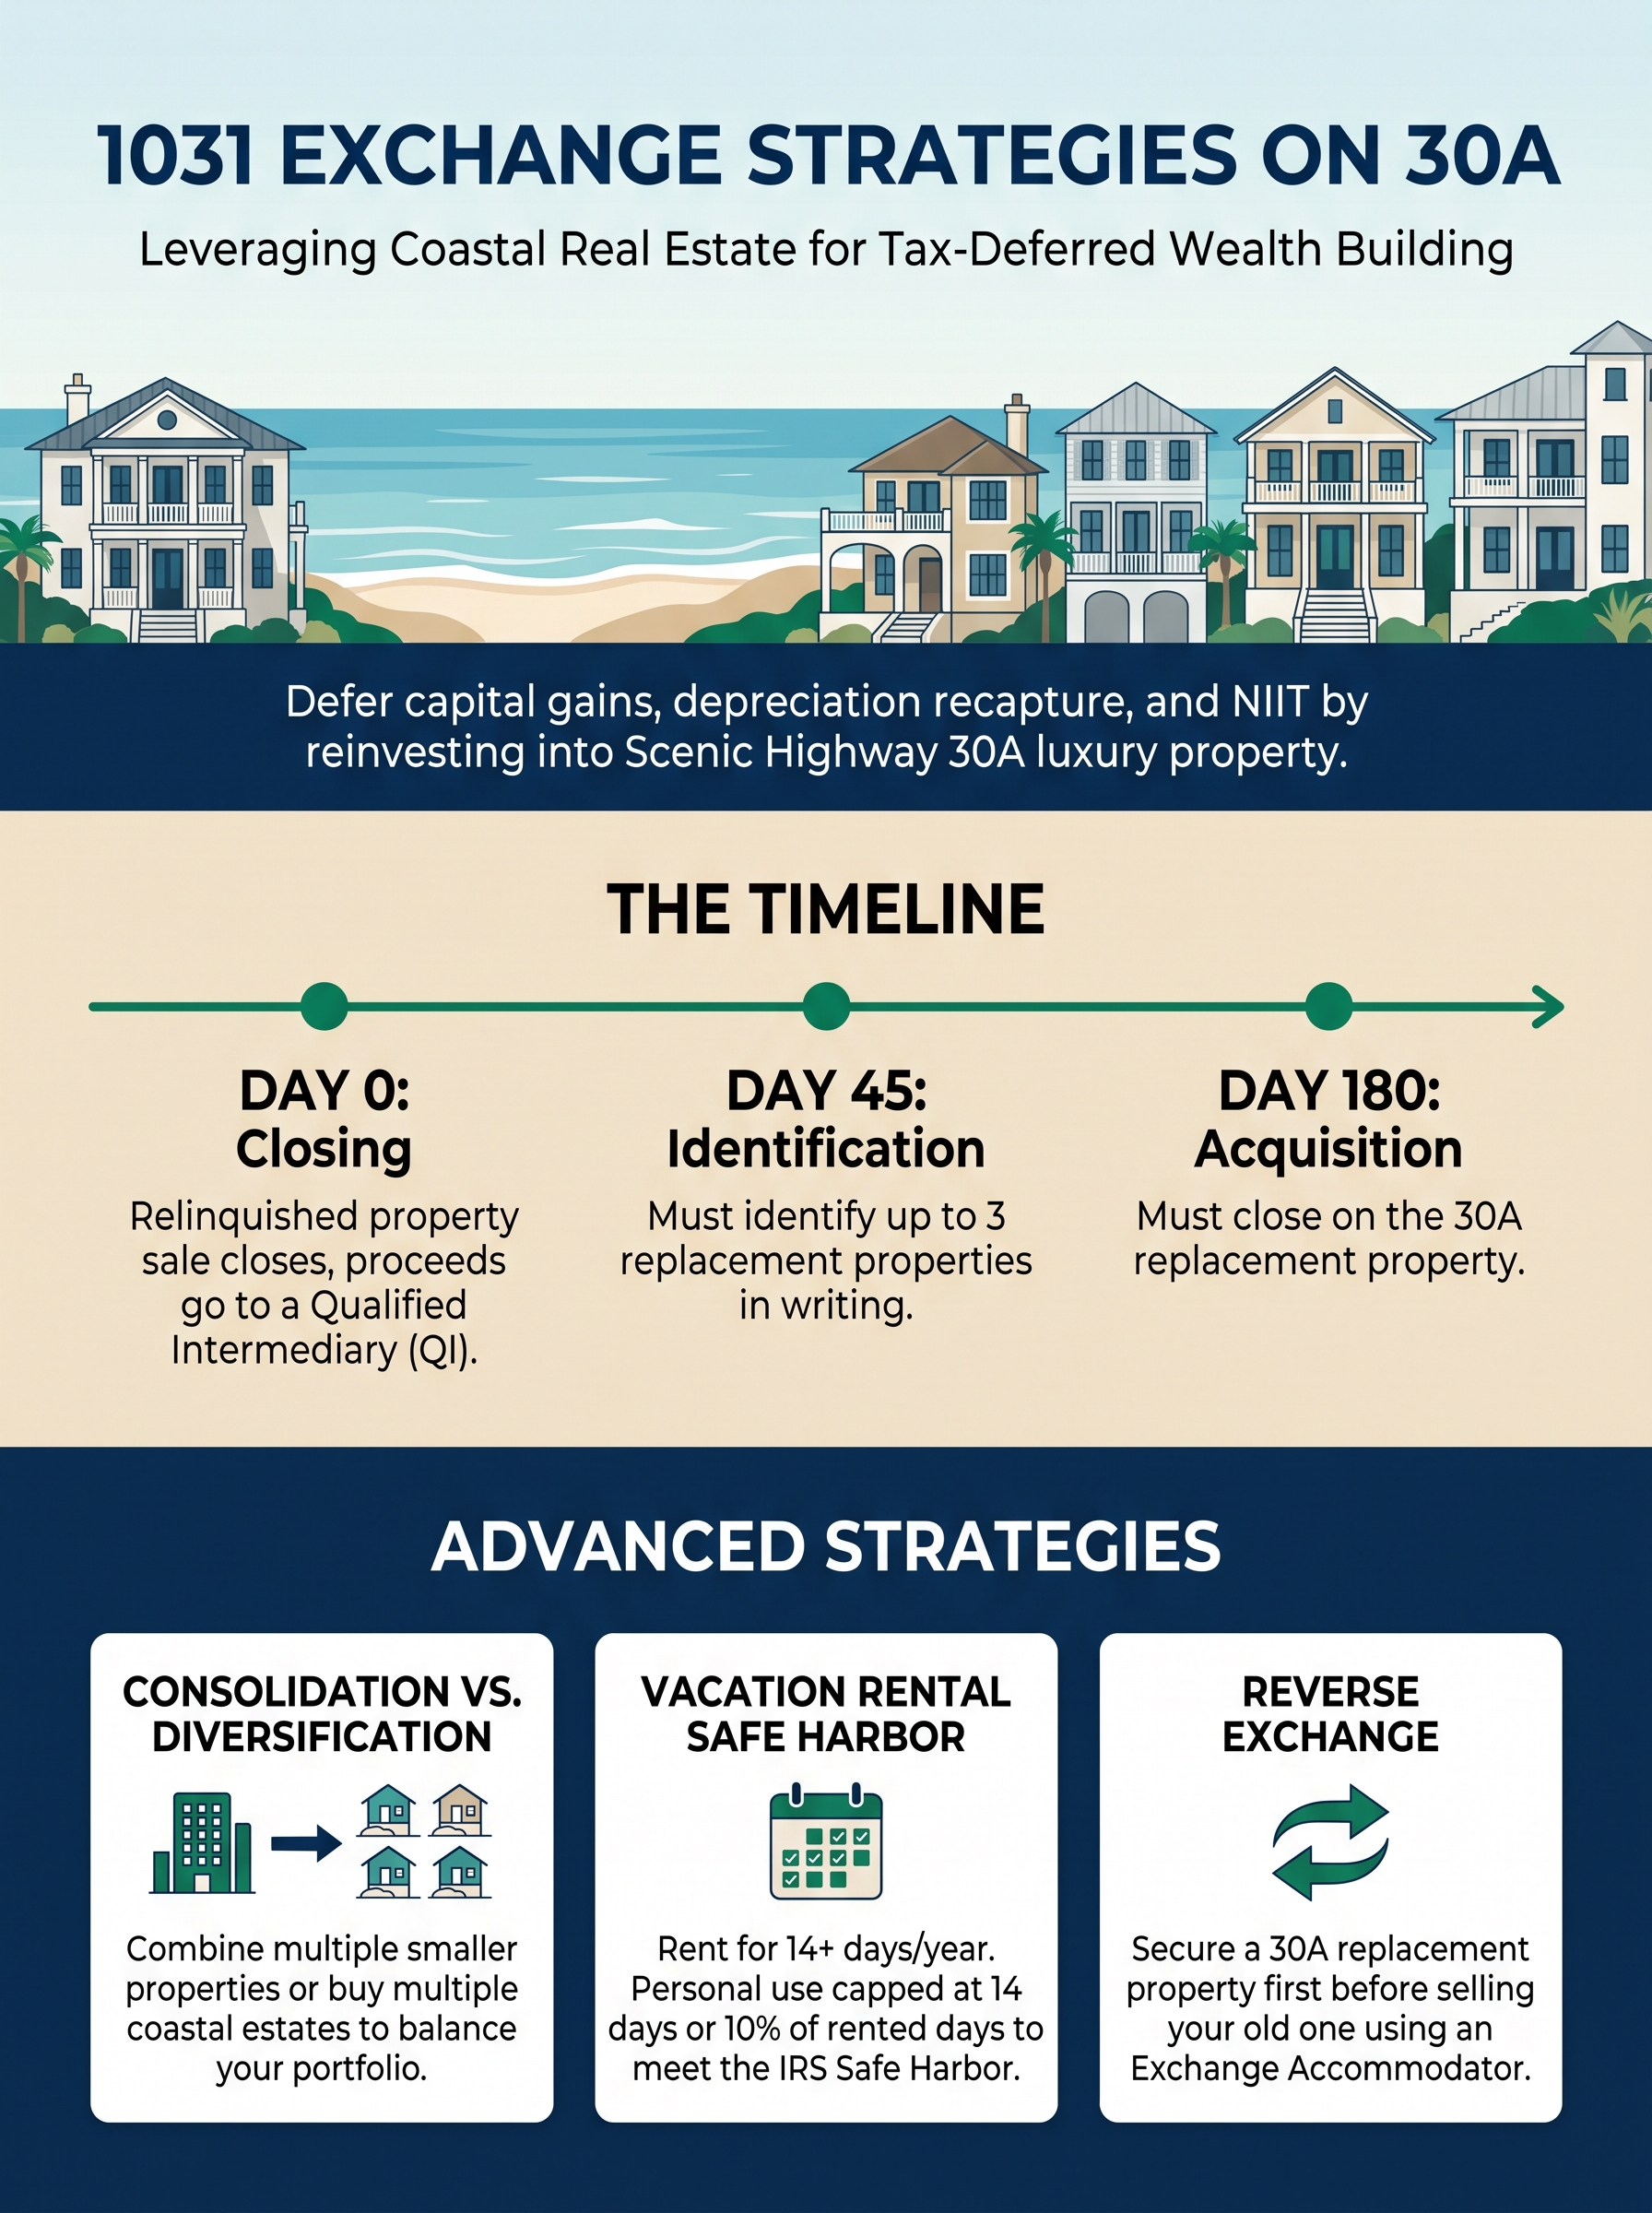
A successful 1031 exchange requires strict adherence to IRS statutory deadlines. Missing a deadline by even a single day invalidates the exchange, triggering immediate tax recognition.
Timeline Milestone | Statutory Requirement | Execution Strategy |
Day 0: Closing Date | The sale of your relinquished property closes. Sale proceeds transfer directly to a Qualified Intermediary (QI). | Ensure the QI is engaged before closing. Funds must never touch your account. |
Day 45: Identification Window | You must formally identify potential replacement properties in writing to your QI. | Identify up to 3 properties (regardless of value) or use the 200% rule for larger portfolios. |
Day 180: Acquisition Deadline | You must complete the acquisition and take title to the replacement property. | Allow ample time for closing, financing, and title work along 30A’s coastal micro-markets. |
Advanced 1031 Strategies for 30A Investors
1. Consolidation vs. Diversification
Diversification: Exchange one high-value commercial building or apartment complex into multiple luxury vacation homes along 30A (e.g., one home in WaterColor and one in Inlet Beach).
Consolidation: Exchange multiple smaller rental properties across different regions into a singular, high-yielding $5M+ beachfront legacy property in Alys Beach or Rosemary Beach.
2. Navigating the Revenue Procedure 2008-16 Safe Harbor (Vacation Rentals)
Under IRS Revenue Procedure 2008-16, a luxury vacation home qualifies for a 1031 exchange if it meets specific rental usage criteria during the first two 12-month periods post-acquisition:
Rental Requirement: The home must be rented to unrelated parties at fair market value for at least 14 days per year.
Personal Use Cap: Personal usage cannot exceed the greater of 14 days or 10% of the number of days the home is rented at fair market value.
After fulfilling the two-year safe harbor period, owners gain enhanced flexibility regarding personal use and long-term estate planning.
3. The Reverse Exchange (Securing Pre-Market 30A Inventory)
In highly competitive coastal markets where prime beachfront properties sell quickly, waiting to close on a relinquished property can mean missing out on target acquisitions. An Exchange Accommodation Titleholder (EAT) can take title to the 30A replacement property first, giving you 180 days to liquidate your existing holding.
Executing a seamless 1031 exchange along Scenic 30A requires coordinating qualified legal advisors, CPAs, qualified intermediaries, and real estate advisors who understand micro-market valuations, HOA covenants, and short-term rental revenue projections.
Disclaimer: This article is for informational purposes and does not constitute tax, legal, or financial advice. Always consult your CPA or tax attorney before initiating a 1031 exchange.
Socials